Friday, October 02, 2026 Facebook | Twitter | Linkedin
Magazine

Mining & Trade News

Malawi Online News
...
Mining

TECHNICAL FILE
September 27, 2026 / By: Rajab Dulaja Economic Geologist - Mineral Exploration and Mining. Graduated from Faculty of Minerals and Petroleum, International University of Africa - IUA, Sudan
...
Mining

ASM Federation hails RBM for increase in gold purchases
September 27, 2026 / Chisomo Phiri
...
Mining

DRAFT MINING LAW HAUNTS KANGANKUNDE
September 27, 2026 / Admin
Mining
Strategic Rare Earths Recovered at Kasiya
July 10, 2026 / Marcel Chimwala

ASX-listed Sovereign Metals has announced a significant and strategic rare earth value addition to its Kasiya Rutile Graphite Project in Lilongwe, Malawi.

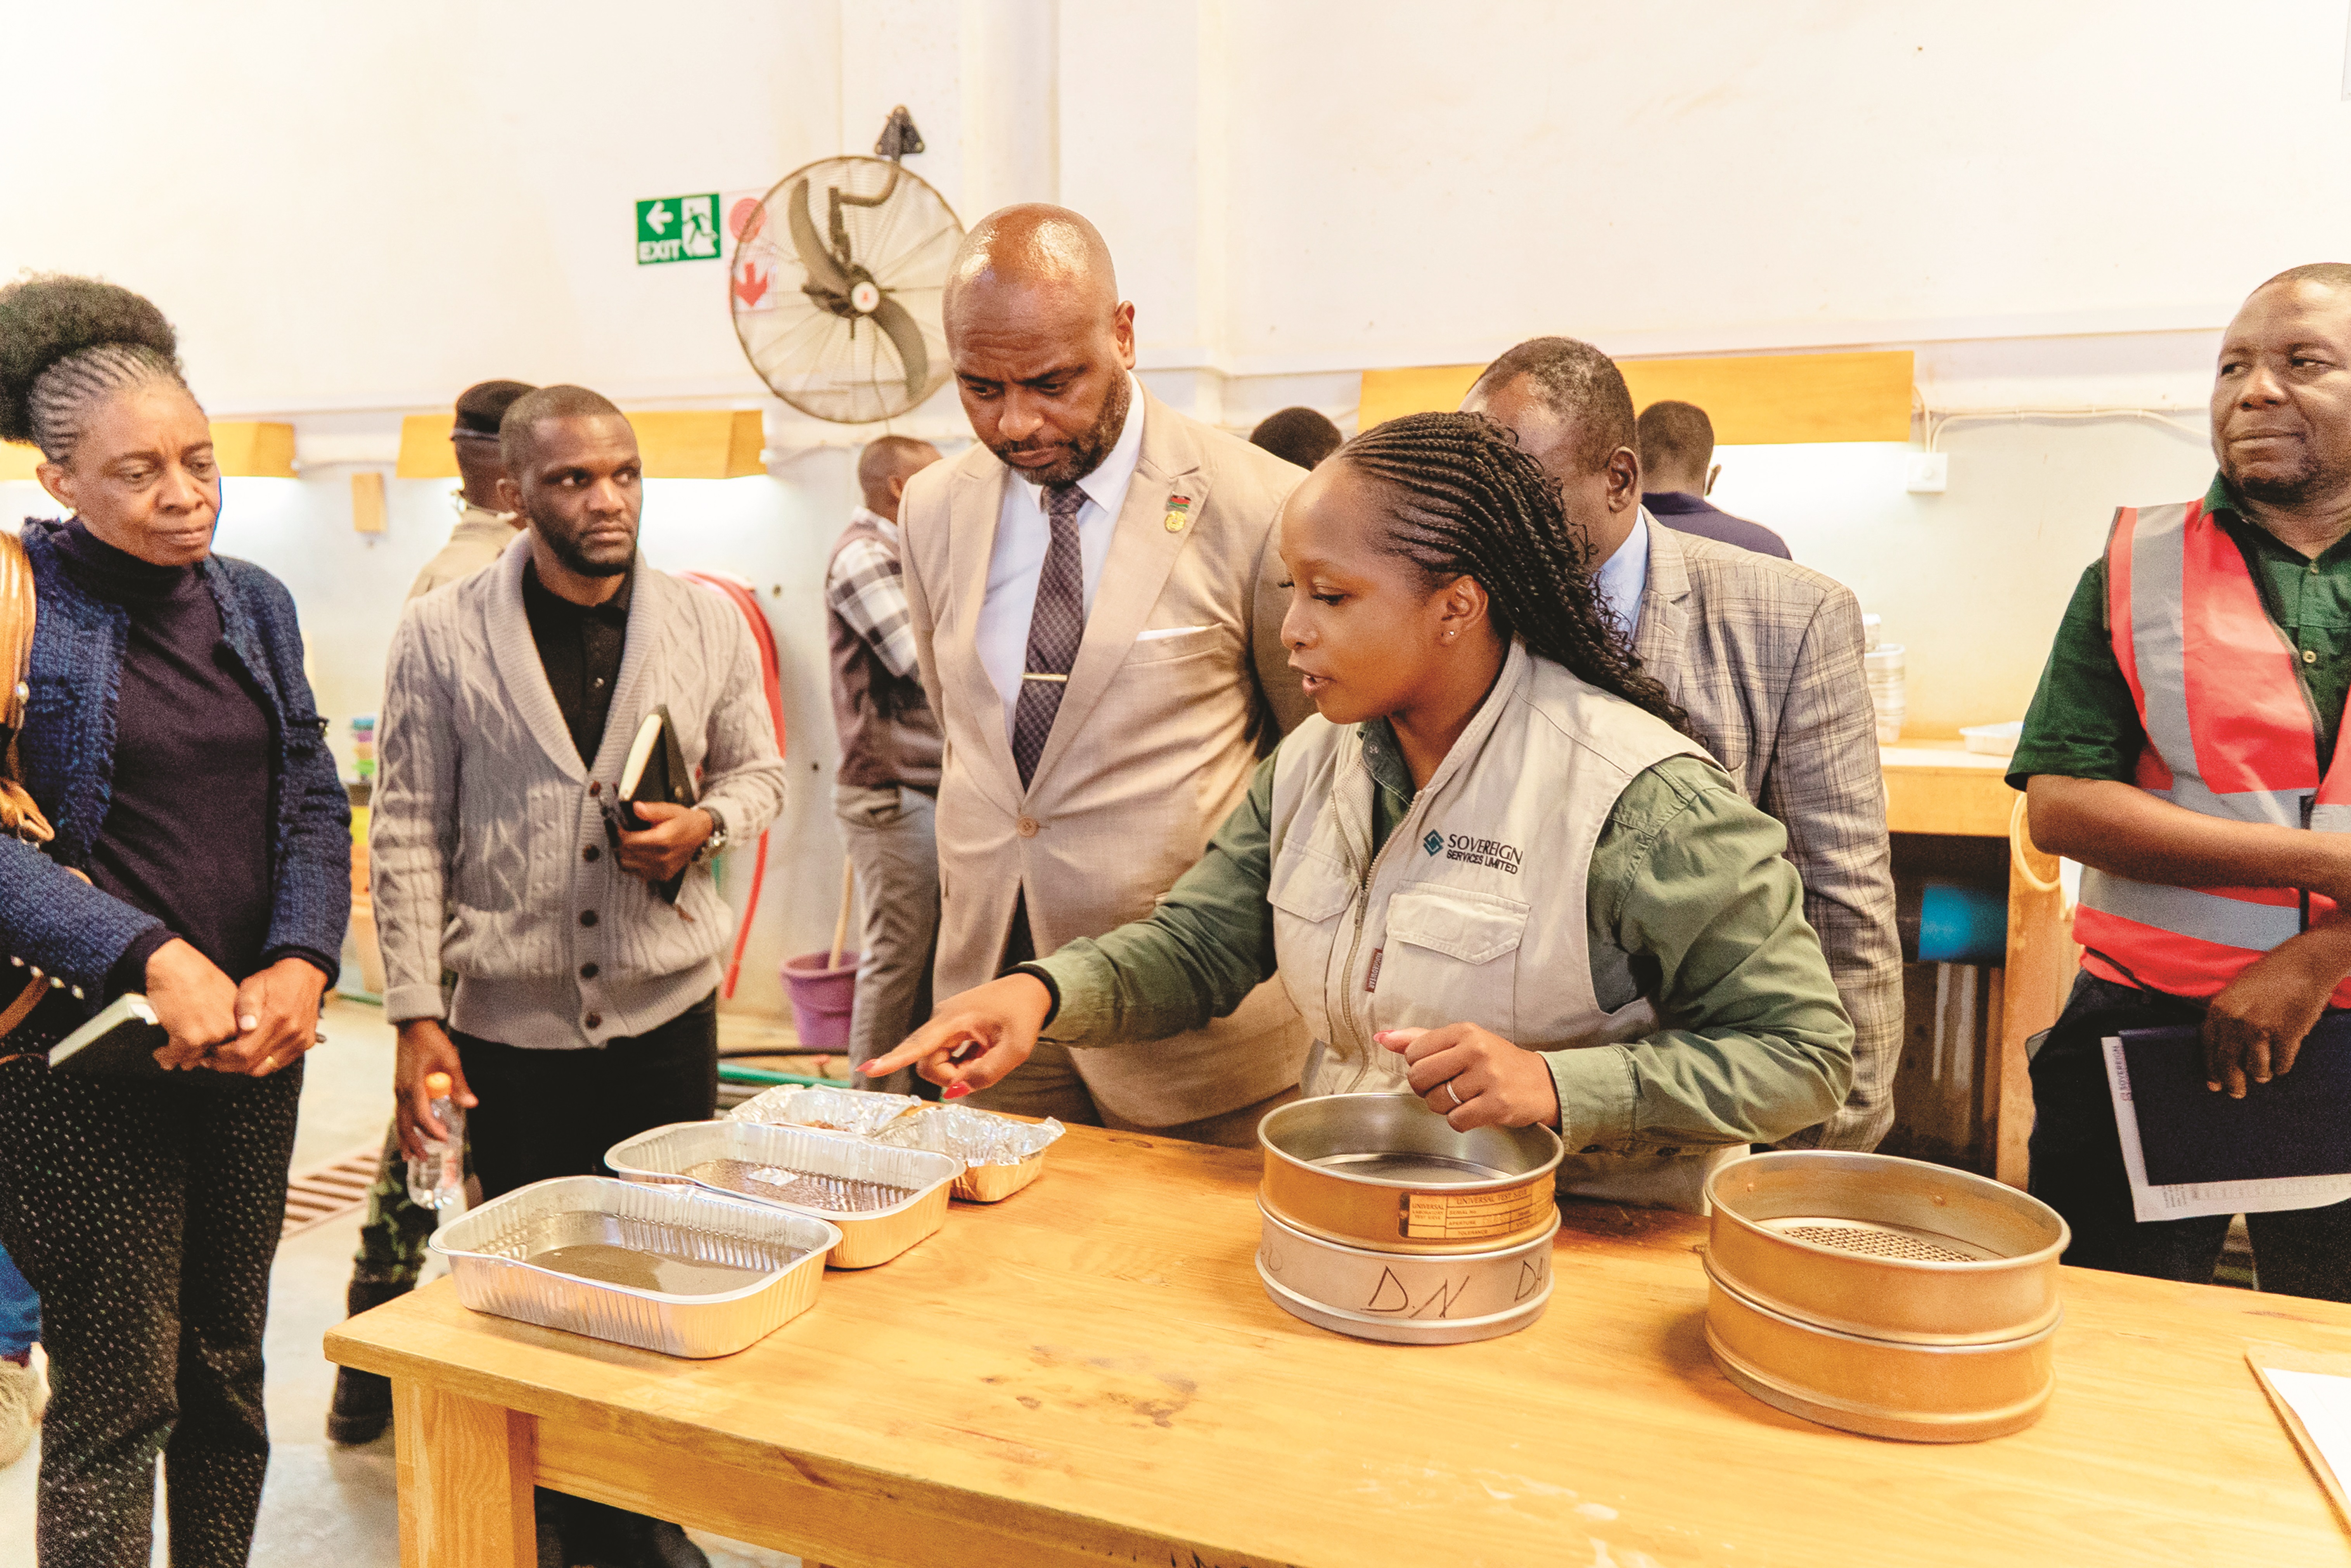
Sovereign’s MD and CEO Frank Eagar says in a statement the Company has successfully recovered a monazite product containing high-value heavy rare earth elements (REE) from the tailings stream generated during rutile processing at its upgraded Lilongwe laboratory facilities.

The concentrate was recovered from material that would otherwise be discarded; the non-conductor tailings stream from electrostatic separation of a heavy mineral gravity concentrate of Kasiya ore.

Eager explains that producing a monazite concentrate would therefore require no additional complex processing.

He states that chemical analysis of magnetic concentrates from processed resource drilling samples performed by Scientific Services South Africa confirmed the favourable rare earth oxide distributions produced from the monazite concentrate.

Preliminary analysis has confirmed the monazite concentrate contains exceptional heavy rare earth content averaging 2.9% (and up to 3.9%) combined DyTb and averaging 11.9% (and up to 17.3%) yttrium, and light rare earth content of 21.8% neodymium-praseodymium (NdPr).

This composition sets Kasiya apart from all major global rare earth producers. The five largest operations – which together account for over 70% of global production – are dominated by light rare earth elements. Strategically critical heavy rare earths urgently required by US, Japan and EU advanced technology, defence, and industrial supply chains are present only in trace amounts, or absent entirely, in these deposits.

Eagar comments: “This is an exceptional development that has the potential to fundamentally enhance Kasiya’s strategic significance. With simple processing, our upgraded laboratory has recovered a valuable monazite concentrate product from the rutile tailings stream, with heavy rare earth content that the world’s major producers simply cannot match.”

“These are precisely the elements that matter most to nations seeking to protect and grow their critical mineral supply chains. Dysprosium and terbium enable permanent magnets to function in advanced technologies, including robotics, fighter jets, guided missiles, and naval propulsion systems. Yttrium protects jet engines and hypersonic vehicles from extreme temperatures. China imposed export controls on all three in April 2025, and Western supply chains are now acutely exposed.”

“What makes this value addition particularly significant is that this product was recovered from our rutile processing tailings stream. We are not currently contemplating a complex, standalone rare earth operation. We have recovered critically strategic rare earths from what would otherwise be discarded – a by-product of the processing route we will use for rutile and graphite production.”

“Kasiya’s rutile will feed aerospace-grade titanium production. Our graphite is essential for battery anodes and traditional industrial applications. And now Kasiya has the potential to also deliver critical heavy rare earths. We have an exciting workstream ahead of us as the potential of the heavy rare earth minerals is delineated. The recent visit by the US State Department to our Malawi operations, combined with our Collaboration Agreement with the World Bank International Finance Corporation (IFC), reflects the strategic importance that governments and institutions are beginning to attach to Kasiya.”

Preliminary analysis versus major global producers  

Global rare earth production is concentrated in five major operations: three in China (Bayan Obo, Weishan, Maoniuping), one in Australia operated by Lynas Rare Earths Ltd (Mt Weld), and one in the United States operated by MP Materials Corp (Mountain Pass). Together, these mines supply over 70% of the world’s rare earth production.

All five are dominated by light rare earths – principally lanthanum and cerium, which are abundant and low-value, and the magnet rare earths Neodymium and Praseodymium (NdPr). The strategically critical heavy rare earths – dysprosium, terbium, and yttrium – that underpin high performance advanced technology, defence, industrial and renewable energy applications are present in much smaller amounts. Kasiya’s heavy rare earth content is approximately 7x higher for both DyTb and yttrium than found in the five largest rare earth producing mines. Mountain Pass – America’s only rare earth mine – contains no measurable DyTb or yttrium.

China’s April 2025 export controls on dysprosium, terbium, and yttrium have created acute supply shortages for Western manufacturers. On January 6. 2026, China announced strengthened export controls on dual-use items to Japan, effective immediately. Despite 15 years of diversification efforts, Japan remains approximately 60% dependent on Chinese rare earth imports. For heavy rare earths, Japan’s dependence on China approaches 100%. Meanwhile, the US is 100% reliant on imports for its yttrium requirements.

Preliminary analysis of Kasiya’s monazite REE content demonstrates one of the highest combined heavy rare earth profiles while maintaining NdPr levels comparable to many REE development projects that have received government backing.

The US State Department visited Sovereign’s operations in Malawi in late 2025 as part of a broader engagement with strategically significant critical minerals projects in Africa.

Rare Earths by-product from existing process

Total rare earth oxide was analysed for in magnetic heavy mineral concentrates produced from aircore drilling samples during laboratory analysis for rutile. The magnetic concentrates were composited by depth interval (0-6m and 6-20m) to assess variation in mineralogy with depth associated with weathering units.

Separately, monazite concentrates were produced from bulk samples processed through the standard Kasiya flowsheet. Gravity concentrates were subjected to electrostatic separation, with the non-conductor stream then subjected to further gravity separation, followed by magnetic separation to produce a magnetic monazite concentrate. Duplicate analyses confirmed excellent repeatability. Chemical analysis to determine the distribution of rare earth oxides was conducted by the Scientific Services South Africa laboratory.

Next steps

Sovereign will now undertake further work to characterise the monazite mineralisation at Kasiya, including:

• Detailed mineralogical characterisation of monazite occurrence and distribution within the Kasiya orebody;

• Assessment of heavy rare earth concentrate recovery rates through the proposed Kasiya processing flowsheet; and

• Evaluation of potential scale of rare earth production as a by-product and associated economics.


Mining
Malawi conducts feasibility study to establish sovereign wealth fund
July 10, 2026 / Wahard Betha

The Malawi Government has initiated a feasibility study for minerals revenue management and development of Sovereign Wealth Fund (SWF).

The study is supported by the UK-funded Malawi Value Chains (MVC) Project, implemented by Adam Smith International, in partnership with the Office of the President and Cabinet – in particular the Open Government Partnership (OGP) Technical Working Group on Natural Resources, the Ministry of Finance and Economic Affairs, and the Ministry of Energy and Mining.

A confidential draft of the Study prepared for stakeholder consultation reads that the feasibility study will provide evidence-based recommendations on the best options for effective management of revenues from mining for the country.

The study also aims to examine the most suitable revenue management systems, including various SWF models, based on evidence of the potential future revenue from the mining sector and economic, political and social context.

It says pecifically, the study will assess the potential scale and timing of revenue from Malawi’s mining sector, and variables that may influence this.

The study will also identify and evaluate revenue management models suited to Malawi’s context, including SWFs.

It will also analyse the potential economic and social costs and benefits of different models; evaluate applicable potential risks and mitigating strategies, drawing from comparable case studies; identify and assess technical, institutional and legal framework barriers and provide recommendations and; develop an actionable implementation plan for the most salient revenue management systems or relevant SWFs tailored to Malawi’s existing policy, legal and regulatory framework

Malawi is positioning itself for a minerals-driven economic transformation, with several mineral prospecting projects anticipated to reach final investment decisions in the next 2-5 years.

The report indicates that based on optimistic revenue projections for six of Malawi’s seven operating or prospective industrial mines (Kayelekera, Kasiya, Malingunde, Kanyika, Songwe Hill and Kangankunde), the Government could collect roughly US$19 million in 2026 and US$622 million in 2036 in nominal terms (US$450 million in real terms).

This translates that Malawi Government could earn not less than US$300 million per year at peak production.

Under optimistic assumptions, these six projects would represent approximately 17 percent of general government fiscal revenues in 2036 (at current rates), less than is currently needed to fill the budget deficit or service the public debt.

As part of its OGP National Action Plan (2023–2025), the Government of Malawi commits to developing a Sovereign Wealth Fund. Before embarking on this journey, the OGP Taskforce thought it wise to first conduct a feasibility study on the establishment of such a SWF.

The report says as major mining projects advance and new investors show interest, Malawi has a window of opportunity to get its policies right.

The insights and consensus built during the consultations will inform a sustainable, inclusive approach to resource management that can serve the nation for generations to come.

Mining
Why Malawi Needs a Critical Minerals Strategy Now
July 10, 2026 / Moses Masingati

Introduction

Human societies have always depended on minerals for their survival and development. From the Stone Age to the Industrial Revolution and today’s digital economy, each phase of progress has been shaped by the minerals it relied upon. What has changed is not the importance of minerals, but which minerals matter most.

In recent decades, a group known as critical minerals has come into sharp focus. Minerals such as rare earths, copper, graphite, and rutile are now needed with global demand expected to double by 2040. Unlike other commodities, CM have supply chains that are geographically concentrated, technically complex, and politically sensitive, making them strategic assets increasingly influenced by geo-politics rather than market forces alone.

As major economies move quickly to secure these minerals and setting up well documented strategies, attention has turned once again to African countries including Malawi.  Yet, despite its endowment of CM, Malawi has yet to clearly define its role in this global supply chain. Without a deliberate strategy, the country risks repeating the historical pattern where resource wealth fails to translate into lasting economic benefit.

2. What are CM and why have they become strategic

There is no universally accepted definition of CM. In most developed economies, they are defined as minerals that are essential to advanced manufacturing, clean energy technologies, and defense systems, but whose supply chains are vulnerable to disruption. While these minerals often overlap with those used in renewable energy, CM are frequently and incorrectly treated as synonymous with green energy transition minerals. In truth however, CM extend far beyond renewable energy in fact, around 60% of the minerals listed as critical by the European Union and United States have no direct energy-transition use. Their criticality instead lies beyond their importance but more towards their vulnerability to supply chain disruptions.

This narrow framing has increasingly been challenged by mineral-producing countries, particularly in Africa, through a simple but important question: critical to whom? Most global critical mineral lists reflect the needs of importing countries, not the development priorities of mineral rich countries.

South Africa, for example, has challenged this narrow view by including coal in its list of CM despite its exclusion from most Western lists. Malawi faces a similar situation. Agro-minerals which Malawi imports such as phosphates and potash for fertilizer production hence at the core of food security, and economic stability, are rarely included in global critical mineral discussions. Yet, from a national perspective, these minerals are more critical than some globally prioritised battery minerals.

Two perspectives therefore dominate the CM debate.

2.1 Importing industrial countires

 The risks of concentrated CM supply became evident in 2010, when China imposed an unofficial restriction on rare earth exports to Japan following a maritime dispute near the Senkaku Islands. At the time, China dominated global rare earth supply, and the disruption led to sharp price increases, exposing the vulnerability of narrowly concentrated critical mineral supply chains. It is against this background that import-dependent industrial economies define criticality primarily in terms of supply security, hence driving policies focused on diversification, stockpiling, recycling and strategic partnerships.

2.2 Resource rich countries

They have increasingly defined criticality by economic opportunity. They are using mineral endowments for long-term economic resilience, job creation and industrialization. This has led to a push on policies that support downstream investments.

Several resource-rich countries have moved beyond simply identifying CM to actively shaping how these resources support national development through deliberate policy choices. One thing stands out CM strategies are shaped by national priorities, not one size fits all global templates.

2.2.1 Asia

Indonesia provides one of the clearest examples of how policy can reshape a mineral value chain. By restricting exports of raw nickel ore and implementing a coordinated industrial policy to support domestic processing, Indonesia has successfully promoted the growth of downstream industries and positioned itself as a global hub for nickel-based battery materials. Mongolia, while operating in a different political and economic context, has also sought to strengthen state oversight and maximise national benefits from its mineral resources through strategic licensing, infrastructure development, and tighter control of mineral exports.

2.2.2 Africa

Across Africa, several countries are beginning to adopt more strategic approaches to CM. Ghana’s green minerals policy emphasizes stronger state participation and align-ment of mineral development with national industrial goals. Ethiopia has focused on tightening licensing regimes and formalising artisanal and small-scale mining to im-prove governance and value capture. Meanwhile, countries such as the Democratic Republic of Congo and Zimbabwe have used export bans or quotas on certain miner-als to encourage domestic processing and increase leverage within global markets.

3. Malawi’s’ strategic role in the global CM value

Malawi’s economy has traditionally been anchored in agriculture, particularly tobacco exports, with mining playing a relatively minor role, contributing less than 1% to the GDP. In recent years however, Malawi is increasingly emerging as a country with significant potential in the global CM landscape.

The country hosts a wide range of critical mineral reserves. According to the Malawi Economic Monitor (2025) published by the World Bank, Malawi is estimated to host around 2% of global rare earth element resources. It is also home to the world’s largest known natural rutile deposit and the second largest flake graphite deposit. Furthermore, Malawi’s average uranium concentration per square kilometer is nearly three times the global average. Although most of these discoveries remain at the exploration stage, their scale and diversity are difficult to ignore.

4. Overview of what Malawi’s CM Strategy Could Look Like

Malawi hosts a wide range of mineral commodities, but not all have high potential to advance national economic objectives. While the Agriculture, Tourism and Mining (ATM) strategy identifies mining as a growth sector, effective policy requires prioritization. Limited institutional capacity and capital mean that efforts must focus on CM where Malawi has scale, comparative advantage, and a viable pathway to value creation.

We also need to understand that criticality is not static. Demand shifts as technologies evolve, substitutes emerge, new reserves are developed, and supply chains diversify. In the mid-20th century, tin was essential for food packaging and electronics and was heavily stockpiled by governments. As aluminium and plastic substitutes as well as new technologies reduced tin use, demand declined sharply. By the mid-1980s, prices collapsed, leaving large stockpiles devalued. Mineral endowment alone creates no value; reserves sitting idle generate neither income nor influence. Only extraction, processing, and market integration convert geology into economic benefit.

To realize tangible gains from the current CM cycle, Malawi needs a clearly articulated national CM strategy. This strategy should guide government policy, coordinate institutions, and align investment toward activities that maximize long-term national benefit rather than short-term extraction.

A Malawi-specific CM strategy could be built around the following pillars:

• Strategic mineral prioritization

Malawi must define its own list of CM based on national development objectives, industrial potential, and geological advantage. An adaptive process should be established to regularly review and update this list as markets and technologies change.

• Targeted and predictable policy instruments

Policy tools such as export controls, “use it or lose it” licensing conditions, and fiscal incentives can accelerate exploration and project development when applied in a targeted and predictable manner. Broad, abrupt, or undifferentiated interventions risk discouraging. It is also imperative to account for cross-border policy interactions when designing domestic CM policies. While the goal is Malawi-specific policies, measures implemented without regard to actions taken in neighboring or competing jurisdictions may fail to produce the intended gains.

• State participation and domestic capital mobilization

Institutions such as MAMICO should be adequately funded and strategically deployed to participate in exploration and downstream processing. Policies should also encourage foreign companies to list on the Malawi Stock Exchange to deepen local ownership and mobilize domestic capital.

• Skills development, research, and institutional capacity

A successful strategy requires sustained investment in skills and knowledge. Universities and technical colleges should develop specialized mining related programmes, while fostering R&D. At the same time, government human resource capacity in mineral valuation, revenue management, and contract negotiation must be strengthened.

• Environmental, social, and governance (ESG) leadership

ESG must be treated as a core pillar of Malawi’s CM strategy, economic gains cannot come at the expense of the very same communities we want to uplift, we must prioritize environmental safeguards and community engagement. ESG compliance comes with economic benefits, For example, Malawi can leverage its hydropower potential to position itself as a low-emissions producer of CM which could enhance marketability and competitiveness in international markets.

• Infrastructure development and value addition

CM development must be supported by investment in energy, transport, and logistics infrastructure. Without reliable infrastructure it will be difficult to link CM to markets as well as develop downstream processing and manufacturing. Drawing lessons from other resource-rich nations, value capture lies in midstream and downstream processing and manufacturing, a direction Malawi must take. However, to be successful, downstream positioning must be incremental and selective, not aspirational across the entire value chain.

• Proper Management of Critical Minerals Revenues

A critical minerals strategy must give equal weight to how revenues are captured and managed. Proper mineral valuation and effective revenue monitoring systems are essential to curb illicit financial flows and ensure Malawi receives fair value from its resources. Fiscal discipline and a clear plan for investing critical minerals proceeds into other productive sectors are necessary to diversify the economy and reduce vulnerability to volatile mineral prices.

• Strategic international partnerships

As a relatively new mining jurisdiction, Malawi cannot achieve its objectives in isolation. Strategic partnerships can attract investment, support technology and skills transfer.

4.1 Existing initiatives

Malawi has already signaled intent through initiatives such as the establishment of the Malawi Mining Investment Company (MAMICO), the plans of creating a sovereign wealth fund, and the ban of raw mineral exports. But intent without strategy achieves little. Recent export bans, implemented without a clear downstream plan, slowed exploration activities while failing to deliver value addition. This is precisely what a strategy is meant to prevent.

5. Conclusion

A successful CM strategy will require discipline, political courage, and patience. It must balance national control with investment momentum, and ambition with realism. The opportunity is real, but it is not permanent. Malawi can either act now with purpose or watch the CM moment pass it by. Additionally, a national critical minerals strategy must move beyond paper and be implemented with urgency. Without action, Malawi will remain policy-rich but outcome-poor. This paper is a call for government, the private sector, development partners, and all Malawians to act together and ensure that Malawi uses its own mineral resources to develop itself sustainably.

Mining
Reassessing Malawi’s Mineral Export Ban:
July 10, 2026 / Percy Maleta

A Call for Pragmatic Reform in the Gemstone and Gold Subsectors

Introduction

The recent bans on the exportation of raw gemstones and other minerals — most notably the 12 February 2025 directive — have reignited debate across Malawi’s mining sector. While the government’s stated goal is to promote value addition and maximize domestic beneficiation, the practical realities show unprepared systems, limited capacity, and unintended harm to the Artisanal and Small-Scale Mining (ASM) subsector.

Emotion Over Evidence:  The Gemstone Dilemma

When the export of raw gemstones was prohibited, the aim was to push for local processing and job creation. However, the implementation was reactive, with limited sector consultation and little recognition of the technical, financial, and structural readiness required. 

The September/October 2025 extension of this ban to all unprocessed minerals deepened the crisis, especially within a gemstone value chain that is fragile but full of potential. A few small processors and entrepreneurs - myself included - have demonstrated that value addition does pay off, through better prices, job creation, skill development, and increased credibility in international markets. However, challenges persist, including:

• Lack of cutting, polishing, and grading equipment.

• Shortage of skilled gem cutters and valuers.

• Absence of gemstone certification and regulatory standards.

• Unstructured markets with limited local demand.

• Irregular production that impedes consistent supply.
The True Art and Science of Gem Valuation

It is important to understand that gemstone processing and valuation go beyond mere cutting or polishing. The value of a gemstone reflects a combination of qualitative factors, including rarity, origin, market and fashion trends, craftsmanship, historical significance, and certification through credible laboratories.

“In today’s global gem trade, trust is the new market currency.”

Unfortunately, Malawi currently has very little of that trust due to inconsistent systems and the absence of internationally recognized certification mechanisms.

Tikuyenera kudekha komanso kuyika ndondomeko zoti zitipititse patsogolo komanso kupindulira dziko — surely not khambakamwa ayi!

We must be patient, structured, and deliberate if we truly want to position Malawi as a credible player in the global gemstone arena.

A Needed Reality Check: Credibility and Global Perception

Let us be honest with ourselves — at times, we have become a laughing stock in the global gemstone community. Having been privileged to work with world leaders in the ethical gemstone trade and as part of the Ethical Gem Show and Chicago Jewellery Transformative Family through my work with Virtu Gem (USA), I have seen firsthand how credibility, transparency, and responsible partnerships define market success.

The ongoing Columbia Gem House (CGH) case — involving Malawi’s purported $309 billion claim — illustrates serious misunderstanding of global gemstone market realities. Consider that Gemfields, the world’s leading ruby producer, has generated around $1 billion in revenues over 13 years — roughly 70% of global premium ruby output. The total global ruby and emerald market is estimated at just $1–2.5 billion per year, making Malawi’s claim economically implausible.

This lawsuit risks damaging our global reputation before we have even established a significant presence. My sincere advice to government is simple: engage, not antagonize. Build bridges with global players like CGH — they bring expertise, ethics, and access to high-value markets, particularly the U.S., the world’s largest gemstone destination. Sustainable value addition is impossible if we isolate ourselves from such critical relationships.

A Smarter Approach: Capacity Before Control

Rather than an outright export ban, Malawi needs a tiered policy approach. Institutions like the Export Development Fund (EDF) could lead gemstone processing initiatives and training programmes while ASMs continue limited exports under transparent frameworks. That way, we promote structured growth rather than pushing small miners into survival mode.

Ultimately, the growth of this subsector hinges on building trust, technical expertise, and internationally recognized systems — not blanket prohibitions.

The Gold Story: Policy Contradictions and Missed Lessons

Parallel to gemstones, the gold business in Malawi has experienced rapid growth. Reports indicate over 90 gold hotspots, with estimated daily output of around 10 kilograms. Through the EDF, the Reserve Bank of Malawi (RBM) has positioned itself at the center of domestic gold trading since 2021, reportedly acquiring about 500 kilograms in total.

However, these official figures raise concerns. Either production estimates are inflated, or significant quantities of gold are being traded illegally, as RBM’s buying prices cannot match parallel market rates.

Adding to the confusion, gold has been removed from the Reserved Mineral Licence (RML) framework - effectively stopping licensed dealers from trading in gold to “protect” RBM from competition - while the same bank buys from unlicensed miners. This contradiction undermines formalization, transparency, and investor confidence.

No genuine investor - local or foreign - will commit to gold mining when they cannot export or access foreign currency. Our policies, though well-intentioned, may be chasing capital out of Malawi instead of attracting it.

Towards a Formalized Gold Economy

Malawi can learn from models such as Tanzania, whose smart regulation and government-private cooperation have turned gold into one of its major forex earners. Malawi should:

1. Reinstate gold under dealer licences (RMLs) for structured private sector participation.

2. Enforce a partial retention scheme,  requiring that 20% of gold be sold to RBM before export — balancing national interest and market freedom. 

3. Establish licensed gold markets in all  major hotspots in collaboration with  Federation of Artisanal and Small-scale  Mining in Malawi (FASMIM), Mining and Minerals Regulatory Authority (MMRA), Reserve Bank of Malawi  (RBM), Malawi Revenue Authorit  (MRA), and local councils

4. Implement a robust certification and  traceability system for legal sourcing.

5. Adopt digital oversight tools rather  than over-policing artisanal players. If managed effectively, gold could easily contribute 40–50% of Malawi’s foreign exchange earnings, making it one of the country’s strongest economic levers.

“We need systems, not suppression — structure, not reaction. The potential is clear if only we let capacity lead policy.”

Building the Foundation: Systems that Work

Both the gemstone and gold subsectors require deliberate, systemic reform. Moving forward, Malawi should: 

• Establish training and processing centers for gemstone cutting, polishing, and gold refining.

• Promote Public–Private Partnerships (PPPs) to build value-addition facilities  and markets.

• Create a Gemstones & Precious Metals Certification Authority aligned with international industry standards

. • Transition policies gradually, engaging stakeholders throughout the process.

• Encourage research, innovation, and global partnerships to strengthen confidence and credibility.

Conclusion

Malawi’s mineral wealth can transform lives and drive structural industrialization — but only through credible systems, realistic policies, and collaborative leadership. Emotion-driven bans may appear patriotic, but they risk killing opportunity and trust.

We must invest in skills, certification, and partnerships, grounding policy in practicality rather than passion. That is how Malawi can move from being a reactive observer to a respected participant in the global gemstone and gold trade.


Mining
Challenges Continue to Dog Minerals Sector in First 100 days of Malawi’s New Administration
July 10, 2026 / Modester Mwalija

As the new administration has completed its first 100 days in office, stakeholders in the minerals sector have acknowledged early positive policy signals in the sector while questioning the absence of concrete reforms, particularly in governance, community protection and Artisanal and Small Scale Mining (ASMs).

Civil Society Organasations working in the sector say the administration has taken a cautious approach, marked more by continuity than decisive reform.

National Coordinator for Natural Resources Jusctice Network (NRJN) Kennedy Rashid, said the government’s performance during the period has been moderate, with limited tangible outcomes.

“The government’s performance during the first 100 days has been moderate but largely cautious. While public messaging has highlighted the importance of mining to economic recovery, tangible outcomes remain limited,” Rashid said.

He said positive signals such as the directive on value addition to minerals have yet to translate into visible actions that improve mining governance, accountability or community outcomes.

Rashid observed that few structural changes have been implemented to restore public confidence, particularly in addressing unlicensed and unregulated ASM activities that continue to affect communities.

He explained that early government statements on investor confidence and the ban on raw mineral exports suggest intent, but deeper reforms remain absent. He cited limited progress on beneficiation frameworks, fair taxation, public disclosure of mining contracts, beneficial ownership transparency and systematic publication of mineral revenue data.

“We have not seen decisive reforms on contract transparency or public disclosure of mining agreements, despite the existence of annual EITI reports,” Rashid said.

He said oversight institutions such as the Malawi Environmental Protection Authority (MEPA) and the Malawi Mining and Mineral Resources Regulatory Authority (MMRA) continue to operate with limited public information-sharing, noting that transparency requires enforceable systems rather than declarations.

For mining-affected communities, Rashid said daily realities remain unchanged, with continued land displacement, environmental degradation, inadequate compensation and weak consultation processes, especially in areas impacted by informal ASM activities.

“There has been no clear improvement in grievance redress mechanisms or community participation, leaving communities excluded from decision-making and disconnected from the promised benefits of mineral extraction,” he said.

Rashid described the absence of a clear reform roadmap within the first 100 days as a missed opportunity saying the government could have outlined timelines for beneficiation, green minerals development, contract review and stronger environmental enforcement.

He called for the immediate publication of mining contracts, licences and revenues, increased state investment through Malawi Mining Investment Company (MAMICO), protection of community rights and the development of a national green minerals’ strategy.

Concerns are more pronounced among ASMs who say recent policy decisions have worsened conditions in the subsector.

Percy Maleta, President of the Federation of Artisanal and Small-Scale Mining in Malawi (FASMIM), said the ban on the export of raw minerals has had a direct and negative impact on ASM operations, which depend heavily on export markets.

“While we welcome the consultations now taking place around export regulations, these should have come before imposing a ban, not after,” Maleta said.

He said access to licences has deteriorated following the suspension of ASM licence issuance and renewal without clear communication. Maleta added that markets remain constrained, noting that the Export Development Fund focuses mainly on gold and top-grade gemstones, leaving the bulk of ASM production without a structured market.

“The ASM subsector is currently in a worse position than at any other time in the history of gemstone mining and trading in Malawi,” he said.

FASMIM has called for the urgent lifting of the export ban, decentralisation of ASM licensing, technical and equipment support through MAMICO, improved gold purchasing mechanisms and a more human-centred approach to mining policy.

From a development and private-sector perspective, ActionAid Malawi says the government has shown goodwill, but policy gaps remain.

In an interview, Project Officer for the Climate Just Transition for Mining-Affected Communities Project at ActionAid Malawi, Charles Finis Phiri, said the government has taken steps to strengthen the legal, regulatory and institutional framework of the mining sector.

“The government has empowered the Ministry of Mining and strengthened the Mining and Mineral Resources Regulatory Authority, which is likely to inspire investor confidence,” Phiri said.

However, he said early actions have created both opportunities and uncertainties, particularly for artisanal miners affected by the raw mineral export ban, while beneficiation and formalisation efforts remain slow.

Phiri said processing minerals locally could maximise revenue, foster industrialisation, create jobs and support the establishment of a Sovereign Wealth Fund. He added that coordination gaps persist, especially around community participation, calling for amendments to extend Community Development Agreements to medium-scale operations and strengthen the role of local councils and traditional leaders.

He said the mining sector has the potential to increase its contribution to Gross Domestic Product (GDP) beyond one percent if supported by investment in beneficiation, institutional capacity building, transparency in licensing and revenue management, local participation and infrastructure development.

From a youth and academic perspective, some progress has been acknowledged, particularly in stakeholder engagement and skills development.

Ezala Banda, a mining student at the Malawi University of Business and Applied Sciences (MUBAS) and a member of the Future Miners Network, said government-led sensitisation meetings involving senior officials have helped improve understanding of mining laws, safety and sustainability among community leaders and local stakeholders.

“These engagements help communities and youths understand how mining should be done legally and safely,” Banda said.

He said the government’s emphasis on value addition positions mining as a pillar of the Agriculture, Tourism and Mining (ATM) strategy, with potential to create jobs and boost national revenue. However, he noted that youth inclusion remains limited, with few practical entry points beyond formal education, and that internships and employment opportunities remain scarce.

Globally, mining remains a capital-intensive sector whose developmental impact depends on strong institutions, effective regulation, value addition and inclusive benefit-sharing. Countries that align mineral extraction with industrial policy, skills development and community participation tend to achieve broader economic gains, while weak governance often limits the sector’s contribution to sustainable growth.

Mining
ACB probes MMRA over suspicious dealings on Kangankunde Project
July 10, 2026 / Marcel Chimwala

The Anti-Corruption Bureau (ACB) says it is reviewing reports on suspicious correspondence between former Mining and Minerals Regulatory Authority (MMRA) Director General Samuel Sakhuta and Rift Valley Resources Developments operating as Lindian Resources.

“The Bureau has received a complaint and will treat it with the urgency it deserves,” says ACB Director Gabriel Chembezi.

Mining & Trade Review has sourced conflicting letters from MMRA regarding exportation of monazite concentrate from Kangankunde mine. A letter from MMRA to Rift Valley dated October 28, 2025 signed by former Director General Samuel Sakhuta, copied to Chief Secretary in the Office of President and Cabinet and Secretary for Mining is headlined “CLARIFICATION NOTE INDICATING THAT RIFT VALLEY RESOURCE DEVELOPMENT LIMITED IS NOT BARRED FROM EXPORTING RARE EARTH AFTER PROCESSING, BENEFICIATION AND VALUE ADDITION AT KANGANKUNDE MINE IN BALAKA IN THE WAKE OF PRESIDENTIAL EXECUTIVE ORDER NO. 2 OF 2025 ISSUED ON 23 RD OCTOBER 2025. “

“By definition when the Mineral ore reaches the level of producing individual rare earth Oxides, it means it has been processed, beneficiated and value addition has taken place. The Authority therefore would like to affirm that your company, Rift Valley Resources Development Limited will not be affected by the Executive Order since your submission clearly shows that you will do value addition to the Monazite Ore right here in Malawi before exporting the product to the market,” reads the letter.

But Lindian published an edited version of the letter in its ASX-release dated October 29, 2025 claiming that Malawi Government had authorized exportation of the monazite concentrate.

Reads the letter with a similar headline and date, and signed by Sakhuta published as part of Lindian’s ASX release: “The Authority therefore would like to affirm that your company, Rift Valley Resources Development Limited will not be affected by the Executive Order since your submissions show that you will do value addition to the Monazite Ore by producing a monazite concentrate through primary beneficiation right here in Malawi before exporting the concentrate to outside markets.”

The stages of processing monazite to rare earth oxides include:

  1. Ore Beneficiation: The monazite ore is crushed, ground, and physically beneficiated to remove impurities.
  2. Chemical Beneficiation: The ore undergoes chemical treatment to extract valuable minerals.
  3. Crystallization: The beneficiated ore is crystallized to produce monazite concentrate.
  4. Monazite Concentrate to Mixed Rare Earth Concentrate: The monazite concentrate is further processed to produce mixed rare earth carbonate and thorium.
  5. Separation of Mixed Rare Earth Concentrate: A separation plant is used to produce mixed RE oxides.
  6. Production of Individual Rare Earth Oxides: The final stage involves the production of individual rare earth oxides based on the desired product.This process is crucial for the production of rare earth elements, which are essential for various applications, including electronics, energy storage, and renewable energy technologies. 

 Lindian, which is scheduled to start commercial mining at Kangankunde in November this year will process the Kangankunde ore locally to Stage 3, which is crystallization to produce monazite concentrate contrary to the mining licence demands and requirements of the Presidential ban on raw mineral exports to process to the final stage which is the production of rare earth oxides as explained by the MMRA in the clarification letter.

The Company has been exporting monazite concentrate to its mixed rare earth concentrate facility in Kazakhstan for tests in readiness for commercial production.

Sakhuta states in the original letter from MMRA: “The Mining and Minerals Regulatory Authority received three different documents in which you include an issue of processing of Monazite Ore.”

“Firstly, your company submitted an application for a mining licence in 2022 in which you included a description that your company will process Monazite Ore into individual rare earth products, such as oxides, thorium or uranium concentrates.”

“Secondly under section 2.4 of the ESIA (Environmental and Social Impact Assessment) Report that your company submitted to Malawi Environmental Protection Authority, there is a mention that the processing of the Monazite Ore shall be up to the level of producing individual Oxides.”

“Thirdly the request that your company made to Malawi Revenue Authority, provides the list of equipment that the company would like to import for the purpose of processing, beneficiating and value addition of the Monazite up to oxides.”

Sakhuta states that the Executive Order is a fundamental national policy instrument for economic diversification and maximization of in country value retention.

But Government is also currently formulating regulations of the raw mineral export ban that contains thresholds for processing of all minerals before export, which also stand as a stumbling block

The Aussie firm purchased mineral rights for Kangankunde, a globally significant rare earth deposit and one of the world’s largest untapped rare earth deposits at US$30-million from locally owned Rift Valley Resource Developments.

Lindian is using Rift Valley’s medium scale mining licence, which has sparked an outcry from members of the Malawi public who want the company to acquire a large-scale mining licence to ensure increased benefits from the project to the impoverished country.

A holder of a medium scale mining licence is not legally required to sign a mining development agreement with government that includes free equity to government as a minority shareholder and a community development agreement as is the case with a large scale licence.

Energy
KASIYA POSITIONED TO SUPPORT US STRATEGIC MINERALS RESERVE AS MALAWI-US PARTNERSHIP STRENGTHENS
July 10, 2026 / Admin

Malawi’s Kasiya rutile-graphite project has moved further onto the global strategic stage following the signing of a memorandum of understanding (MOU) between Sovereign Metals and Traxys North America – one of only three trading houses appointed to procure critical minerals for the US Government’s newly launched US$12 billion Project Vault.

Sovereign Metals, through its Malawi subsidiary Sovereign Services, is developing Kasiya near Lilongwe as a future leading supplier to the global titanium and graphite industries.

Project Vault is a landmark US public-private initiative to establish a US Strategic Critical Minerals Reserve, aimed at securing supply chains for American manufacturers and reducing reliance on Chinese-controlled mineral supply. The programme is backed by US$10 billion from the US Export-Import Bank and approximately US$2 billion in private capital.

Under the MOU, Traxys will work towards marketing graphite from Kasiya, targeting initial volumes of about 40,000 tonnes per year, increasing to up to 80,000 tonnes annually as the project expands.

Graphite is designated a US critical mineral and is considered essential for national security and supply chain resilience. With global supply dominated by China, alternative sources are strategically vital. Kasiya’s natural flake graphite, together with its globally significant rutile resource – a key source of titanium – positions Malawi as a potential long-term supplier to aerospace, defence, advanced manufacturing and battery supply chains.

Traxys’ role in Project Vault creates a direct commercial link between Malawi’s Kasiya Project and the US strategic minerals reserve. The initiative has attracted participation from major US manufacturers including General Motors, Boeing and Google.

The announcement comes amid strengthening engagement between Malawi and the United States. At the 2026 Mining Indaba in Cape Town, representatives of Sovereign and Traxys met with a senior US Department of State advisor, while Malawi’s Minister of Mining participated in US State Department discussions, highlighting the growing Malawi–US partnership in critical minerals.

Sovereign Metals Managing Director and CEO Frank Eagar said the agreement reflects growing international confidence in Malawi’s strategic role.

“Through Kasiya, Malawi has the opportunity to become a key contributor to secure and diversified supply chains for the United States and its allies,” he said.

The MOU, which contemplates a potential 5–10-year marketing arrangement, marks an important step in positioning Malawi as a trusted long-term partner in Western critical minerals security. - Langmead & Baker

Mining
From “Mineral Criticality” to Economic Opportunity:
July 10, 2026 / Ignatius Kamwanje

Can Malawi Turn Global Energy Transition Demand into National Development?  

Series: Malawi’s Critical Minerals Moment

By now, you may have heard the phrase critical minerals—often mentioned alongside electric vehicles, renewable energy, and growing geopolitical tension. But what exactly makes a mineral “critical,” and to whom? Why are major global economic powers such as the United States and China scrambling to secure their mineral supplies? And what does all this mean for Malawi, a country whose geology is increasingly attracting international attention?

Despite the confident way the term is used, “critical minerals” are not a formal scientific mineral category. They are defined politically and economically. A mineral is considered critical when it is essential for use in modern renewable technologies but are vulnerable to supply chain disruptions. Different countries publish different lists, depending on their industrial priorities and national security concerns. However, most include minerals required for renewable energy systems, advanced electronics, and defence industries, among them being rare earth elements, graphite, lithium, cobalt, uranium, titanium (including rutile), tantalum, and platinum group metals.

Their importance becomes clearer when we consider where they are used. Lithium, graphite, cobalt, nickel, and manganese power electric vehicles, smartphones, and large-scale renewable energy storage systems. Rare earth elements are indispensable for highperformance permanent magnets used in wind turbines and electric vehicle motors. Copper and aluminum underpin power grids, transmission lines, and electrification systems. Uranium is regaining prominence as countries reconsider nuclear energy as a low-carbon baseload power source for climate change mitigation. In short, these minerals form the material foundation of the technologies shaping the 21st century and decarbonization initiatives. Without them, the global push toward decarbonization, digital connectivity, and advanced manufacturing would stall.

This growing dependence has transformed minerals into a geopolitical issue. For decades, global resource geopolitics revolved around oil. Today, competition increasingly centers on critical mineral supply chains, from extraction to processing and manufacturing of high-tech digitalization. The challenge lies in their geographies. Many critical minerals are mined in developing countries in the Global South, while refining, processing and even consumption are spatially concentrated in the Global North. Rare earth processing, for example, is heavily dominated by China, even though deposits are distributed globally. Such concentration creates supply “chokepoints,” where economic disruptions, export controls, or diplomatic tensions can have worldwide consequences.

As a result, critical minerals are now framed as national security priorities to minimize changes of weaponization by the dominating countries. To this effect, governments are funding mining projects abroad, signing long-term offtake agreements, fast-tracking “strategic” projects, and forming diplomatic alliances centered on mineral access including on shoring strategies. What was once a commercial commodity discussion has become a strategic race.

Against this backdrop, Malawi has emerged as a country of growing importance. Several projects are drawing international attention. Songwe Hill in Phalombe, developed by Mkango Resources, is one of Malawi’s most advanced rare earth projects. Rare earths are crucial for magnets used in wind turbines and electric vehicle motors, linking the project directly to global renewable energy supply chains. In Balaka district, Kangankunde, developed by Lindian Resources, is widely described as a globally significant rare earth deposit. On the Lilongwe Plain, the Kasiya project combines rutile, a high-grade titanium mineral used in aerospace and pigments, with graphite, a key battery material. Meanwhile, in Karonga, the Kayelekera uranium mine has been reopened after more than a decade of inactivity, placing Malawi back into the global uranium market at a time when nuclear energy is being reassessed worldwide.

These projects signal that Malawi is no longer on the margins of global mineral conversations. Yet the classification of these resources as “critical” is not neutral. What is critical for one country may not be critical for another. The designation often reflects industrial strategy and geopolitical interests rather than geological scarcity alone. By labeling a mineral “critical,” governments elevate it to strategic importance, justifying accelerated investment, policy support, and diplomatic engagement. However, producing countries frequently bear the environmental and social costs associated with extraction. This raises important questions. Who defines what is critical? For whose benefit? And at what cost? Local communities in producing regions may not necessarily view these minerals as “critical,” particularly if mining operations disrupt land, water, or livelihoods. While global industries depend on these resources, the burdens of extraction are often localized. If not carefully governed, the rush for energy transition minerals can replicate familiar patterns of inequality and green capitalism.

There is also the complexity of dual use. Many minerals powering renewable technologies also support defence systems. Lithium batteries power electric vehicles, but they also power warfare unmanned aerial vehicles and advanced communications systems. Rare earth elements are essential in wind turbines and in missile guidance systems. This overlap between civilian green technologies and military applications adds another layer of geopolitical significance and raises deeper questions about the nature of the energy transition.

For Malawi, the central question is not simply whether these minerals are critical globally, but whether they can become transformative nationally. Minerals are finite resources. Once extracted, they are depleted. The economic development opportunity presented by this global demand is real, but it is not automatic. Resource-rich countries have historically faced the risk of the so-called “resource curse,” where mineral wealth fails to translate into broadbased development.

To avoid this outcome, Malawi must focus on strategic governance. Mining agreements should prioritize transparent revenue systems, stable fiscal terms, local procurement, skills development, and enforceable community benefit mechanisms. The goal should be predictable public income and economic multipliers that extend beyond the lifetime of a mine. Where feasible, value addition should be encouraged, whether through mineral upgrading, beneficiation, or partnerships that support domestic processing capacity. While not all minerals can be fully processed locally in the short term, incremental steps can increase value retention.  

Institutional strength and capacity will be equally important. Clear licensing systems, credible environmental oversight, contract transparency, and empowered regulatory bodies can build both investor confidence, public trust and ultimately social license to operate. Investors seek clarity and efficiency; citizens demand accountability and safeguards. Effective mineral governance can reconcile these two seemly conflicting interests.

Mining revenues, if managed prudently, can also finance long-term development priorities. Investments in reliable electricity, transport infrastructure, technical education, and industrial diversification can ensure that mineral wealth supports economic resilience long after extraction ends. Increasingly, global buyers are under pressure to demonstrate responsible mineral sourcing to contribute to achieving the sustainable development goals This presents Malawi with an opportunity to position itself as a jurisdiction that emphasizes environmental protection, water stewardship, community participation, and transparent governance, thus, turning responsible mining into a competitive advantage rather than a constraint.

Ultimately, Malawi may benefit from defining its own critical minerals strategy. The one grounded not only in global demand but in national development objectives and priorities. Rather than responding passively to external classification systems, the country can articulate what minerals are strategically important for its own economic transformation and how extraction aligns with long-term sustainability.

Critical minerals are reshaping the global economy, and Malawi possesses geological assets that the world increasingly wants. From rare earths to rutile, graphite, and uranium, the country stands significantly at a competitive advantage. The question is no longer whether Malawi can attract mining investment, it already has. The deeper question is whether it can convert this global rush into inclusive, sustainable national development. With strategic negotiation, strong institutions, value addition, and community-centered governance, Malawi’s critical minerals moment could become more than a mining boom. It could become the foundation for long-term economic transformation. 

Mining
Stakeholders tips Govt. on corruption eradication in mineral sector
June 06, 2024 / Wahard Betha

Stakeholders acting in the extractives sector has tipped the Malawi Government through the Ministry of Mining on some of the incentives to reduce corrupt practices in the mineral sector.

Commenting during a panel discussion on Zodiak Television, Human Rights Advocate for Centre for Human Rights and Rehabilitation (CHRR), Loveness Thole said the government has all it is needed to fight corruption in the extractives sector and what is needed is the enforcement of the laws.

Thole said for the Government to ensure that corrupt practices within the sector has been reduced, they require to enforce containments of the new Mines and Minerals Act of 2023.

“Government should just enforce what is in the laws. Our laws contain almost everything including manning any corrupt practices.”

“What was lacking in the old act was enforcement and I believe if the ministry can enforce what is the new law, no any corruption can happen within the sector,” said Thole.

In his remarks, Consulting Geoscientist, Igneous Kamwanje urged for unity within the sector in order to put to an end corruption in the sector.

Kamwanje further appealed to Malawi Extractives Industry Transparency Initiative (MWEITI) to perform its duties including implementing some of the recommendations written in annual reports.

“We need to have unity of direction. Would love the MWEITI to be performing its duties. Almost every year they produce reports and what is written in their reports every year it does not work on the ground.”

“The non-state actors like them, they bring in checks and balances in terms normalization and bringing in standards in enforcement of the laws. For the corruption to end the people needs to be united and there is a need for disclosure of information.”

“Because when the information is disclosed to the public we both move in one direction and everyone know where we are going.”

“Despite that mining is at infant stage but there is a lot that is going on in terms of institutions which is overlaps in some of its mandates creating a room for corruption,” said Kamwanje.

The panel discussion was organized in line with Empowering Stakeholders Driving Just Resources Governance through open Contracting and Licensing Project being championed by Perekezi Consultancy under empowering Just Energy Transition (JET) minerals challenge with funding from USAID.

In a separate interview, Representative for Perekezi Consultancy Chikomeni Manda advised the government to be transparent in some of the processes conducted within the sector to ensure no deal is suspicious to the general public.

Manda also tipped the ministry to ensure speed process of contracts and licenses saying delays for finalize the documents influences the investors to indulge in corruption to meet the deadline.

He said: “The government should ensure transparency in how they handle licensing issues to build public trust and confidence.

“It is also very important to reduce the long waiting time for licenses as the more it delays, the investor resort to corrupt practices with the aim of speeding the process,” he said.

Meanwhile, a number of Mining Development Agreements (MDAs) are still in pipeline awaiting final approval by the ministry of mining.